During the earnings call with its parent company, Sands China reiterated its quarterly EBITDA goal of $700 million
Sands China EBITDA slips to US$430mn in the second quarter
Article by:
PUBLISHED:
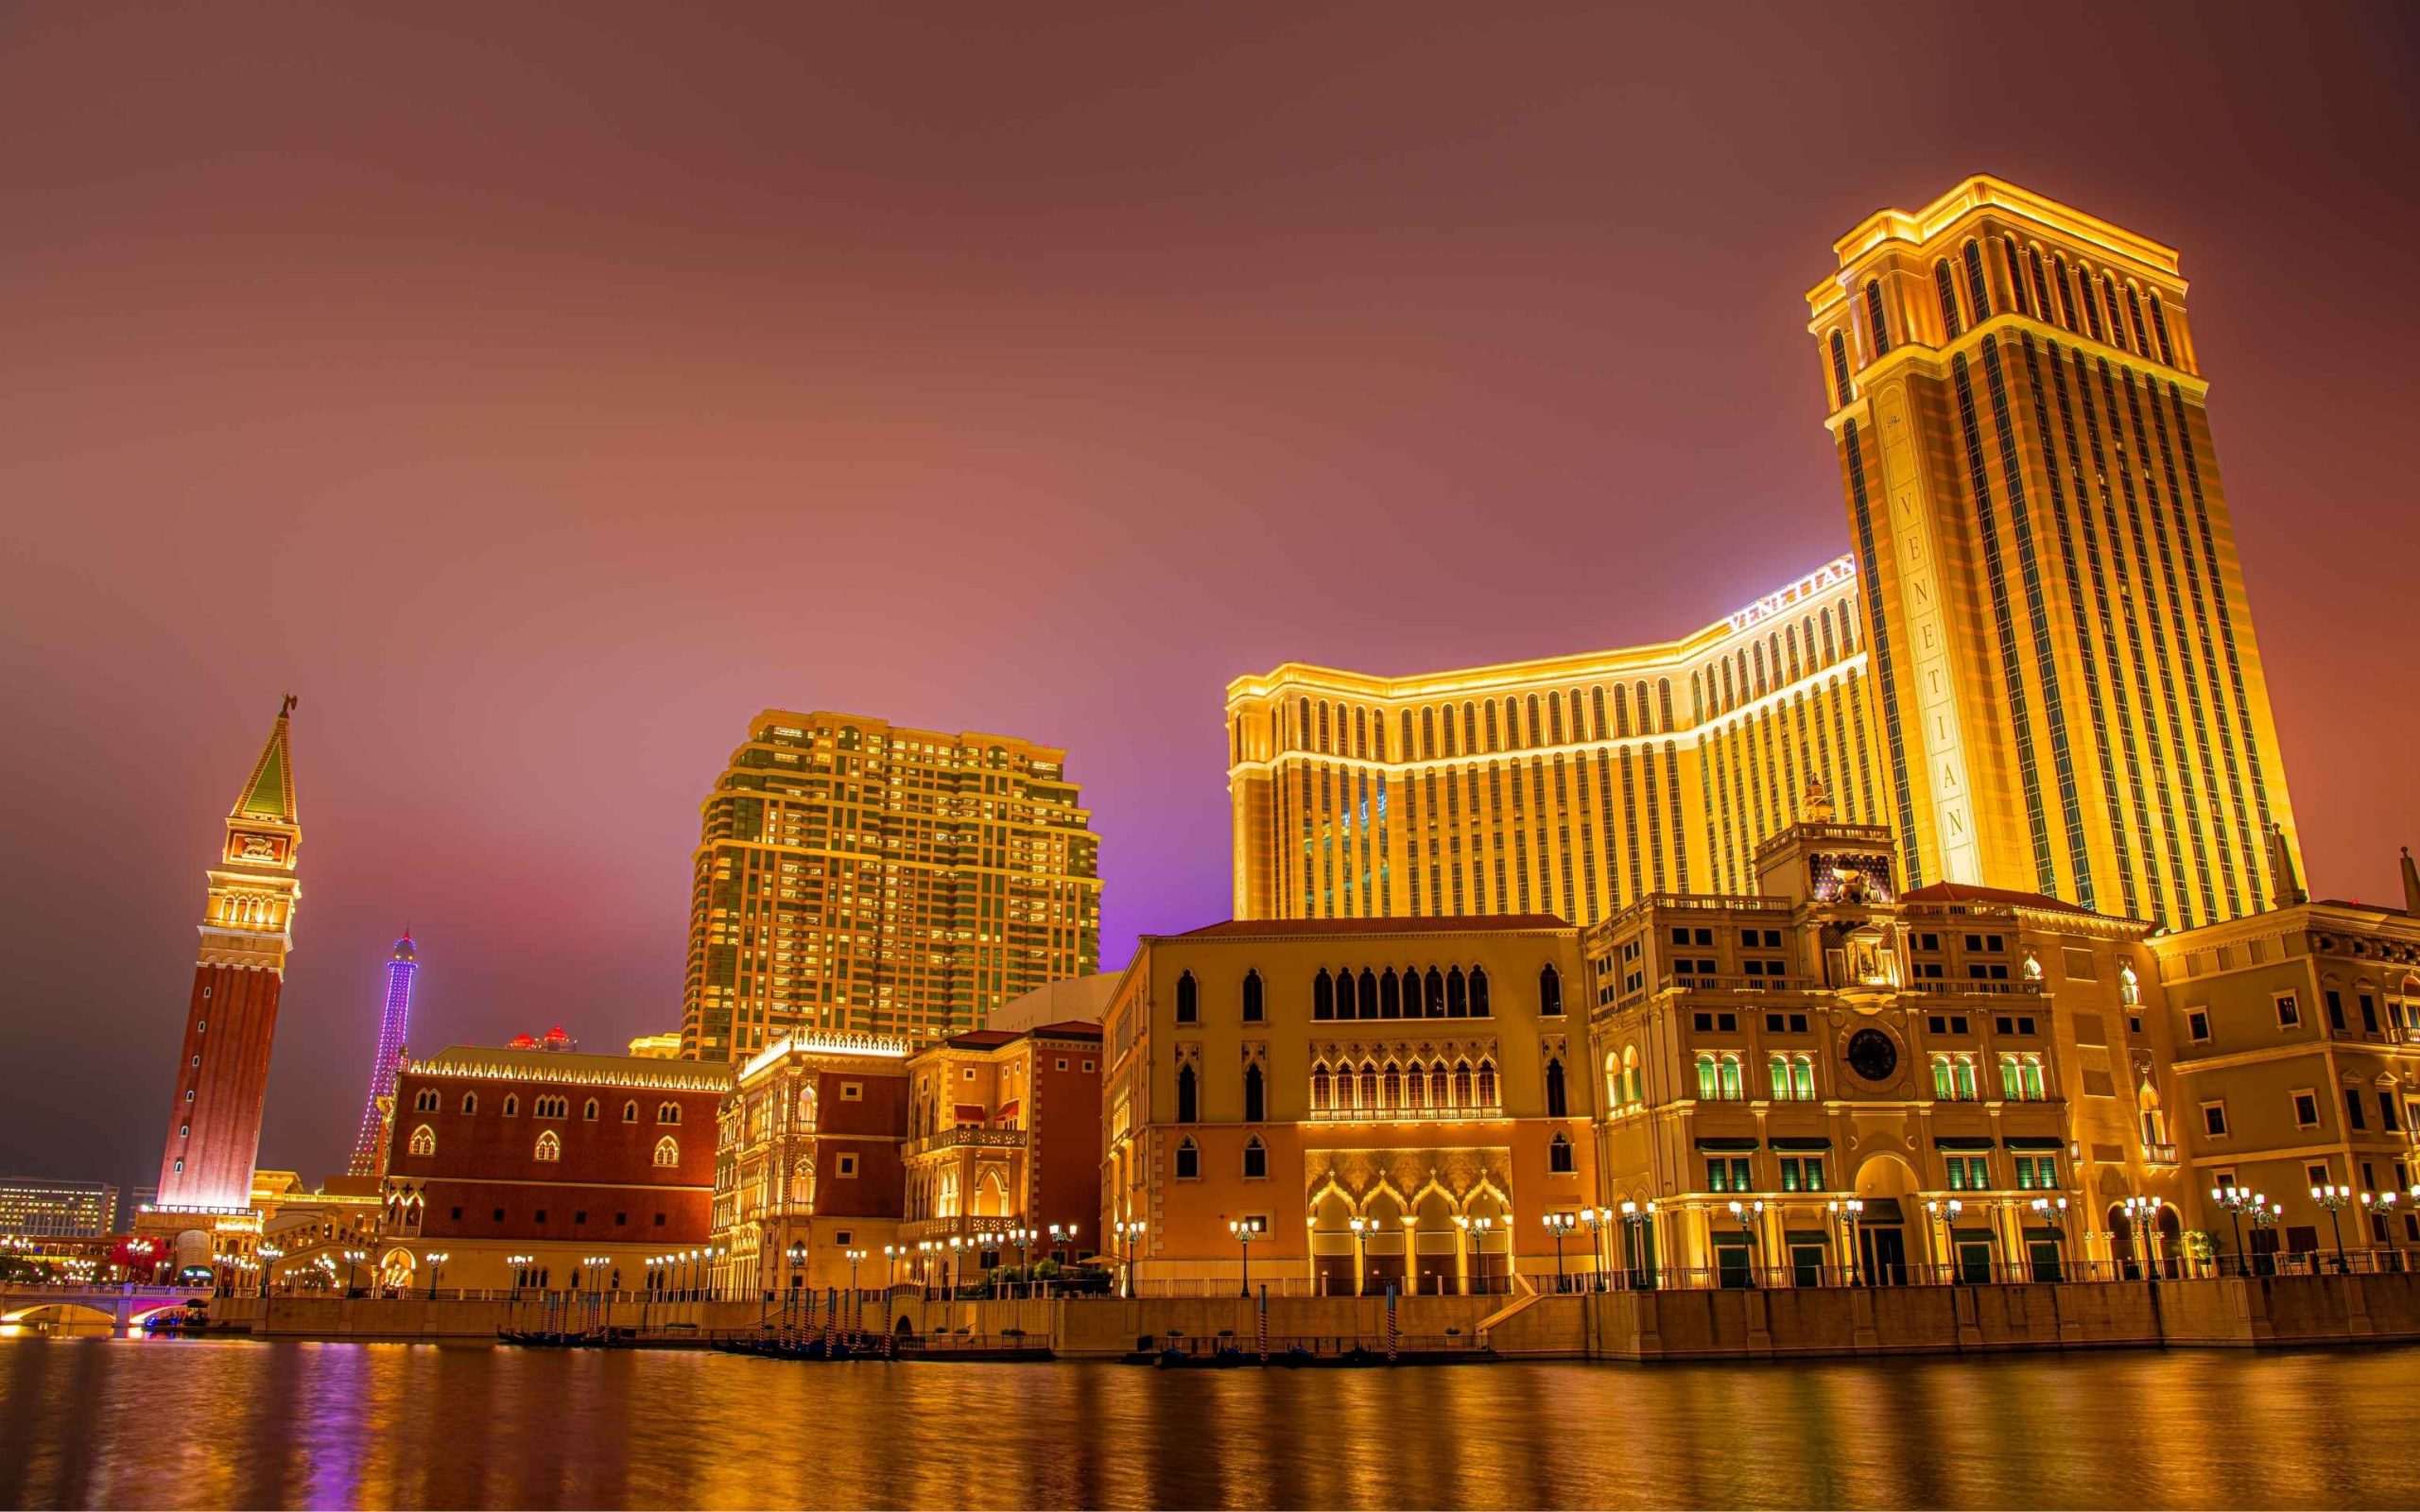
New York-listed Las Vegas Sands reported its second-quarter results early this morning, which included unaudited financial numbers for its Hong Kong-listed Sands China subsidiary.
For the three-month period ended June, total net revenues for the group’s Macao operations fell 0.8 percent to US$1.8 billion from the same quarter a year ago. Property earnings before interest, taxes, depreciation, and amortisation (EBITDA) came in at US$430 million, a 24 percent drop from the US$566 million achieved in the second quarter of 2025.
With Macao’s market revenue growth led by the highly competitive premium segment, EBITDA margins contracted to 24 percent from 31.5 percent a year ago. In addition to ongoing investments to enhance service levels and customer experiences, refreshed premium suites continue to weigh on operating margins and cash flow, with property upgrades, including at the Venetian Macao, set to continue through 2028.
Sands China’s second-quarter EBITDA came in below market expectations. In addition to seasonality, numbers were negatively impacted by this year’s FIFA World Cup. Both the Macao operations and Las Vegas Sands’ Marina Bay Sands in Singapore reported a decrease in visitations among their high-value patrons during the tournament, which featured 104 matches compared to 64 contests four years earlier.
[See more: Macao’s gambling revenue dips in the second quarter, as football bets rise]
Besides property spending and the World Cup factor, management noted that Sands China’s lower EBITDA was also impacted by an exceptionally low VIP hold rate of 1.35 percent. Had rolling chip volume held as expected, the group stated that EBITDA would have reached US$517 million, or US$87 million higher.
For the quarter, Sands China reported mass gross gaming revenue growth of 8 percent, outpacing the market’s 4 percent growth, while its total GGR rose by 4 percent. During the earnings call, management reiterated the goal of reaching US$700 million in quarterly EBITDA over time as investment and operating strategies are fully implemented. There was no change in CAPEX guidance.
[See more: Macao’s gambling revenues set for an August pickup: Jefferies]
Second-quarter earnings are the first since Hubert Wang, former president and chief operating officer (COO) of MGM China, was hired as the new chief operating officer of Sands China on 1 June. Parent company Las Vegas Sands announced that it did not purchase any additional shares of its subsidiary, holding its ownership level at 74.8 percent as of the end of June 2026.
Based on CLSA estimates, Sands China is trading at a 2027 EV/EBITDA multiple of 8.8x, with the brokerage maintaining an ‘Outperform’ rating. Earlier this month, gaming analyst Jeffrey Kiang published a Macao patron survey showing that an increasing number of potential visitors plan to pivot their visits from the second quarter to the fourth quarter or first quarter of next year.
“Demand for Macao tourism remains healthy,” Kiang shared with The Bay. The analyst noted that while curbs on cross-border capital flows remain a sector headwind, this year’s CLSA survey shows that more than 90 percent of respondents plan to fund their gambling budgets using either cash or UnionPay cards, which is in line with last year’s findings.